Introduction
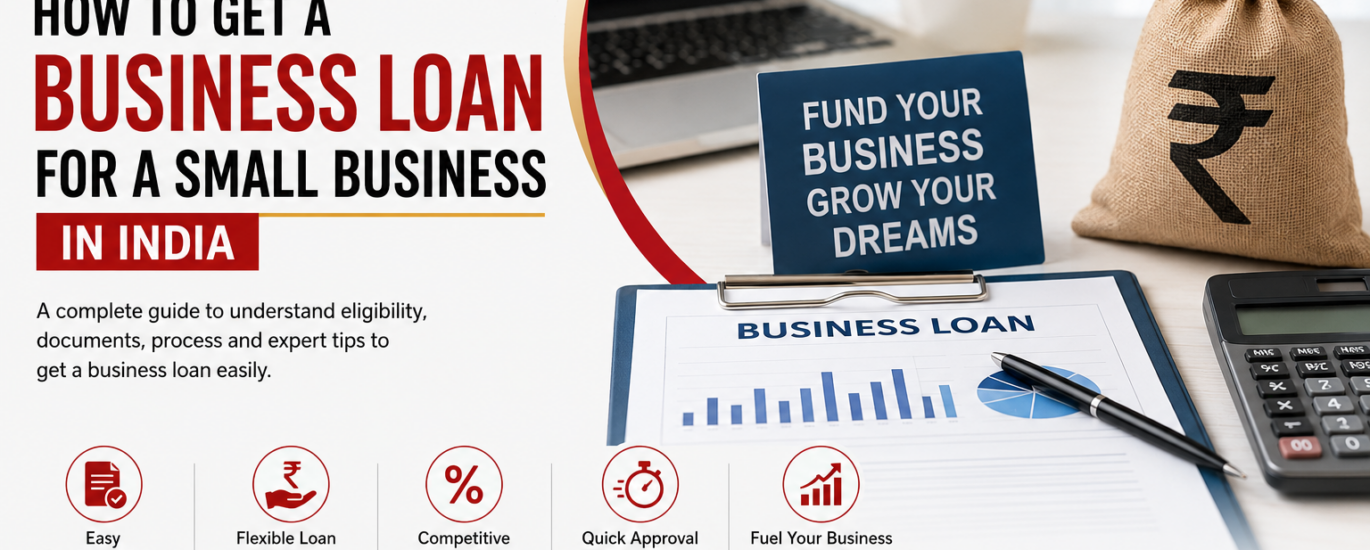
Access to adequate funding is one of the biggest challenges faced by small businesses in India. Whether you’re launching a new venture, expanding operations, purchasing equipment, managing working capital, or increasing inventory, a business loan can provide the financial support needed to achieve your goals.
However, many entrepreneurs struggle with understanding the loan application process, eligibility criteria, documentation requirements, and lender expectations.
In this guide, we’ll explain how to get a business loan for a small business in India and improve your chances of approval.
What is a Business Loan?
A business loan is a financial facility offered by banks, NBFCs (Non-Banking Financial Companies), and other financial institutions to help businesses meet their operational and growth requirements.
Business loans can be used for:
- Working capital requirements
- Business expansion
- Machinery and equipment purchase
- Inventory management
- Hiring employees
- Marketing and business development
- Infrastructure development
Types of Business Loans Available in India
1. Working Capital Loans
Designed to manage day-to-day operational expenses such as salaries, rent, inventory purchases, and vendor payments.
2. Term Loans
Suitable for business expansion, machinery purchase, or long-term investments.
3. Secured Business Loans
Loans backed by collateral such as property, machinery, or fixed deposits.
4. Unsecured Business Loans
Loans provided without collateral based on business performance and creditworthiness.
5. Loan Against Property (LAP)
Business owners can leverage commercial or residential property to obtain funding at competitive interest rates.
Eligibility Criteria for Business Loans
While eligibility requirements vary among lenders, most institutions evaluate the following factors:
Business Vintage
Most lenders prefer businesses with at least 2–3 years of operational history.
Annual Turnover
A stable and growing turnover improves loan eligibility.
Credit Score
A good credit score demonstrates responsible financial behavior and increases approval chances.
Profitability
Lenders analyze profitability trends and cash flow management.
Banking Transactions
Healthy banking records indicate business stability and repayment capability.
Industry Profile
Certain industries may be considered lower or higher risk depending on market conditions.
Documents Required for a Business Loan
Generally, lenders require:
Business Documents
- GST Registration Certificate
- Udyam Registration (if applicable)
- Business Incorporation Documents
- Partnership Deed or MOA/AOA
Financial Documents
- Income Tax Returns
- Profit & Loss Statements
- Balance Sheets
- Bank Statements (6–12 months)
- GST Returns
KYC Documents
- PAN Card
- Aadhaar Card
- Address Proof
- Passport-sized Photographs
Step-by-Step Process to Get a Business Loan
Step 1: Assess Your Funding Requirement
Determine how much funding is needed and how it will be utilized.
Avoid borrowing excessively, as higher debt obligations may impact profitability.
Step 2: Evaluate Your Loan Eligibility
Review your:
- Credit score
- Turnover
- Profitability
- Existing debt obligations
Identifying weaknesses beforehand can improve approval chances.
Step 3: Choose the Right Loan Product
Select a loan product that aligns with your business objectives.
For example:
- Working capital needs → Working Capital Loan
- Expansion plans → Term Loan
- Asset-backed funding → Loan Against Property
Step 4: Prepare Financial Documents
Ensure financial records are updated and accurate.
Strong documentation builds lender confidence.
Step 5: Submit the Application
Apply through a bank, NBFC, or financial advisor who can help identify the most suitable lending options.
Step 6: Credit Assessment and Approval
Lenders conduct:
- Financial analysis
- Credit appraisal
- Risk assessment
- Business evaluation
Step 7: Loan Sanction and Disbursement
Upon approval, the lender issues a sanction letter and disburses funds according to agreed terms.
Common Reasons Business Loans Get Rejected
Many small business owners face rejection due to avoidable mistakes.
Common reasons include:
- Poor credit score
- Insufficient business history
- Inadequate cash flow
- High existing debt
- Incomplete documentation
- Irregular banking transactions
- Weak financial statements
Understanding these factors can significantly improve approval chances.
Tips to Improve Business Loan Approval Chances
Maintain a Strong Credit Score
Pay existing EMIs and credit card dues on time.
Keep Financial Records Updated
Maintain accurate bookkeeping and financial reporting.
Improve Cash Flow Management
Healthy cash flow indicates repayment capability.
Reduce Existing Debt Burden
High debt-to-income ratios can impact eligibility.
Prepare Professional Financial Projections
Lenders prefer businesses with clear growth plans and realistic projections.
Seek Expert Financial Guidance
Professional financial advisors can help structure loan applications effectively and connect businesses with appropriate lenders.
Why Professional Loan Advisory Matters
Navigating business financing can be complex.
An experienced financial advisor can:
- Assess funding requirements
- Improve loan eligibility
- Structure loan proposals
- Prepare CMA data and projections
- Coordinate with lenders
- Accelerate approval timelines
This significantly increases the likelihood of securing the right funding solution.
Conclusion
Obtaining a business loan for a small business in India requires careful planning, proper documentation, and a clear understanding of lender expectations.
By maintaining strong financial records, improving creditworthiness, and selecting the right loan product, business owners can successfully access the capital needed to grow and scale their operations.
If you’re looking for expert guidance on business loans, working capital funding, or structured finance solutions, Swastik Financial Solutions can help you identify the right funding options and support you throughout the lending process.
Need Business Funding?
Contact Swastik Financial Solutions today for expert assistance with business loans, working capital finance, debt advisory, and funding solutions tailored to your business needs.